
Dar es Salaam — Savings and credit cooperative societies ended 2025 with assets of Sh1.69 trillion, nearly 16 per cent higher than a year earlier, but their average non-performing-loan ratio stood at 8.1 per cent, above the sector’s 5 per cent limit, a new performance report found.
The report, launched at the 26th SACCA Congress in Dar es Salaam, identifies loan quality and inadequate institutional capital as the most immediate risks facing a sector intended to widen affordable finance for households, workers, farmers and small businesses.
By the end of 2025, the country had 981 licensed SACCOS serving about 1.9 million members and beneficiaries. Their assets rose by 15.8 per cent, net loans reached Sh1.41 trillion, and members’ savings and deposits rose to Sh1.22 trillion, according to the report presented at the congress.
But the growth was driven largely by existing members saving and borrowing more, not by a comparable expansion in membership, which rose just 2.7 per cent. The report said 90 SACCOS were undercapitalised and required attention in 2026.
“Trust is the most valuable asset of SACCOS,” Prime Minister Mwigulu Nchemba told delegates. He said the sector could replace buildings, upgrade technology and raise capital, but that its institutional foundation was shaken when trust was lost.
Gains alongside pressure points
SACCOS are member-owned financial cooperatives that mobilise savings and make loans, often serving people and enterprises that may not use conventional banks. Under the Microfinance Act, they form tier three of the microfinance system, placing them within a framework for licensing, regulation, supervision and consumer protection.
READ MORE: New Cooperative Bank Set to Transform Tanzania’s Agricultural Financing
The 2025 report recorded Sh181 billion in income and Sh25 billion in profit before tax. It also showed that costs consumed 86 per cent of income, slightly above the 85 per cent ceiling used by the registrar, while institutional capital was below the six per cent minimum even though core capital remained above its 8 per cent requirement.
The lending portfolio has become a defining issue. Net loans made up 83 per cent of assets, above the report’s 70 to 80 per cent benchmark, while long-term lending almost doubled and bad loans exceeded the sector’s five per cent threshold.
The report also points to a concentrated market. The 22 largest SACCOS held 60 per cent of the sector’s assets, while 769 of the smallest held less than 11 per cent, exposing a wide difference in the capacity of institutions operating under the same cooperative model.
There were signs of improved financial reporting: the share of SACCOS receiving clean audit opinions rose to 46 per cent from 34 per cent, and adverse opinions fell below three percent.
Still, the report said 2026 priorities should include restoring institutional capital, controlling costs, reducing bad loans, closer oversight of large SACCOS and resolving the position of the undercapitalised societies.
Turning savings into investment
The sector’s scale gives it a significant role in financial inclusion. Formal financial-service use rose from 65 per cent of adults in 2017 to 76 per cent in 2023, according to the Bank of Tanzania’s Financial Inclusion Report, while SACCOS accounted for 1.87 million savings accounts that year.
READ MORE: Development From Below? This Is the Story of a Daladala Co-op in Dar es Salaam
The most recent annual inclusion report recorded a 24.7 per cent fall in SACCOS loan accounts in 2025, to 1,043,309, even as the value of loans issued rose eight per cent to Sh1.31 trillion. The central bank attributed part of the decline in accounts to the deregistration of SACCOS that did not meet licensing requirements.
At the congress, Nchemba argued that the next stage should shift cooperative lending towards productive uses in agriculture, livestock, fisheries, manufacturing, trade and small enterprises.
“Our challenge, therefore, is to transform African savings into African investments, African investments into African enterprises and African enterprises into African jobs,” he said.
Digitalisation is central to that strategy but remains incomplete. The 2025 report said 268 SACCOS used core digital systems and more than 140,000 members used mobile applications or USSD services, yet only a little more than one in four societies had a core system.
READ MORE: Tanzania’s Women Entrepreneurs Seek Alternatives to Predatory ‘Blood-Sucking’ Loans
Nchemba said digital tools should bring services closer to farmers, entrepreneurs, women and young people, but must be matched by cyber security, data protection and consumer confidence.
The report also found that young people represented 37 per cent of members but only 11 per cent of board members, while women held more than 32 per cent of board seats.
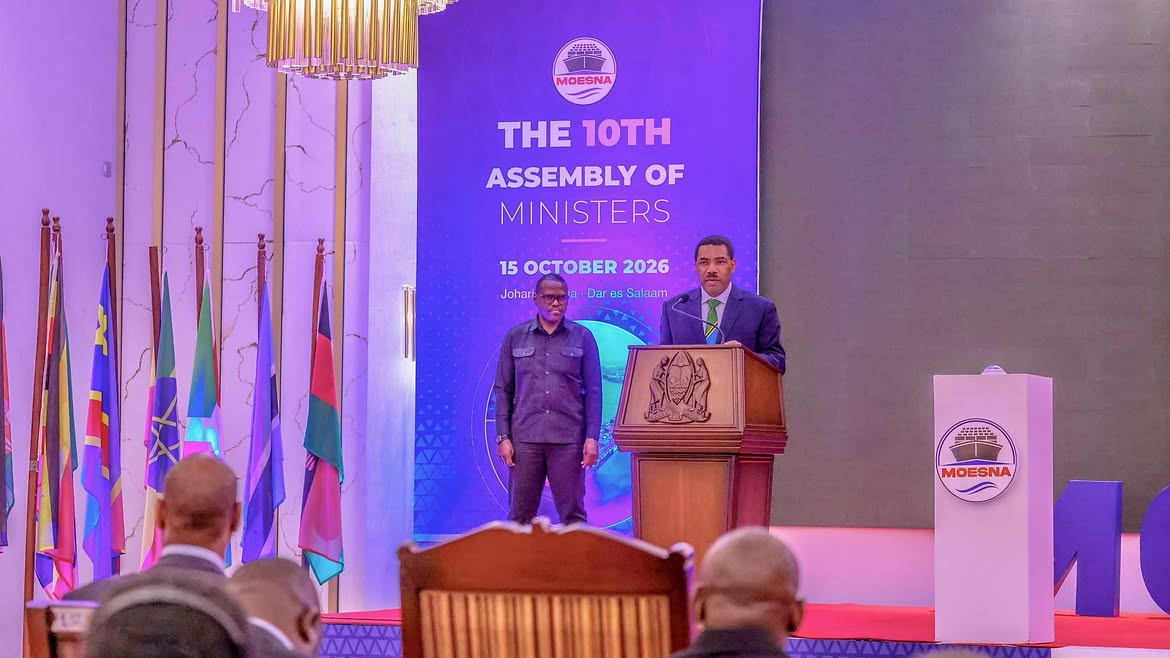
The ACCOSCA congress, held from October 11 to 16 at the Julius Nyerere International Convention Centre, was expected to bring together about 1,200 delegates from Tanzania, other African countries and beyond.
Its theme, Building Trust, Driving Transformation, put governance, digital innovation and member protection at the centre of a discussion about how cooperatives can grow without putting members’ savings at greater risk.